How to understand Duration gap?
485 播放时长:744
加载播放器...
How to understand Duration gap?
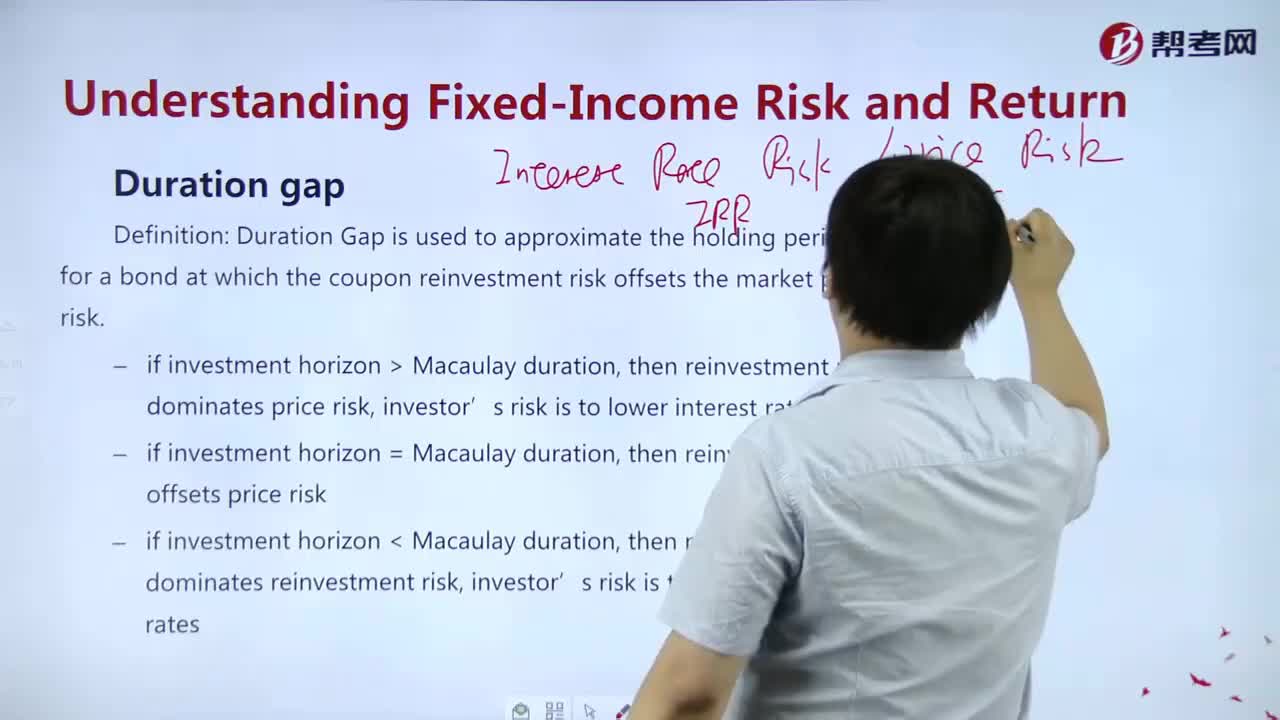
Duration gap is a measure of the sensitivity of a financial institution's assets and liabilities to changes in interest rates. It is calculated by subtracting the weighted average duration of liabilities from the weighted average duration of assets. The result is a measure of the net duration of the institution's portfolio.
A positive duration gap means that the institution's assets have a longer duration than its liabilities, indicating that it is more sensitive to interest rate increases. Conversely, a negative duration gap means that the institution's liabilities have a longer duration than its assets, indicating that it is more sensitive to interest rate decreases.
Duration gap analysis is an important tool for managing interest rate risk in financial institutions. By understanding the duration gap, managers can identify potential vulnerabilities in their portfolios and take steps to mitigate the risk of interest rate fluctuations.
CFA考试视频CFA一级视频How to understand Duration gap?