Portfolio Expected Return and Variance of Return
473 播放时长:992
加载播放器...
= 8112 = 9. Thus:RjB.C.FirstEXY = EXEY
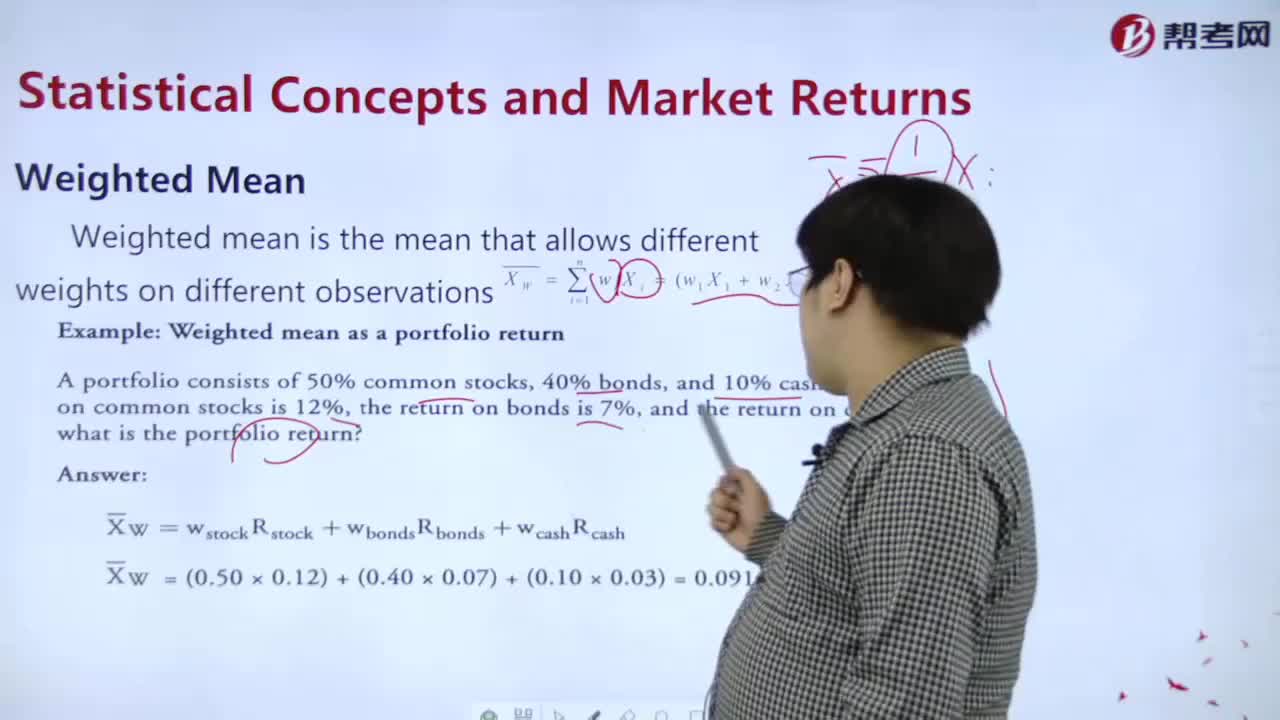
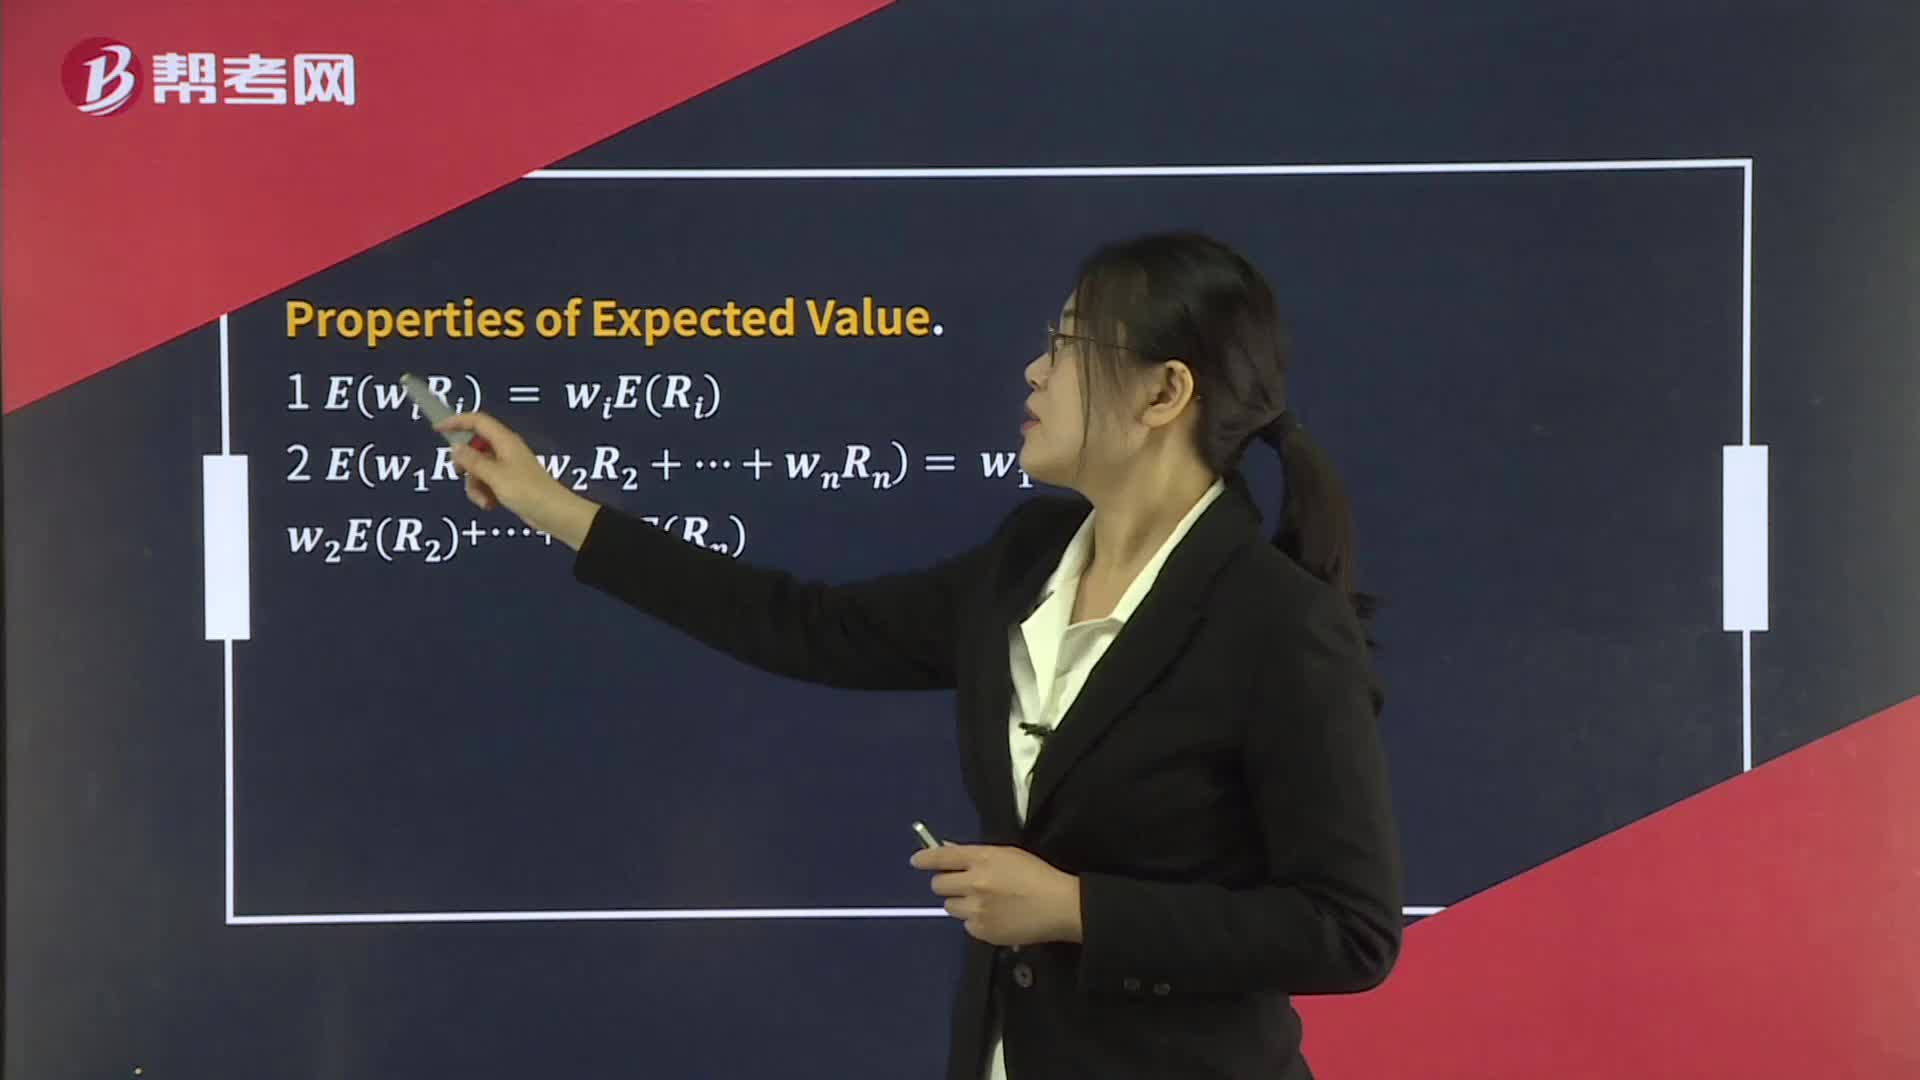
The portfolio expected return is the weighted average of the expected returns of the individual assets in the portfolio. It is calculated as follows:
Portfolio Expected Return = ∑(Weight of Asset i x Expected Return of Asset i)
For example, if a portfolio consists of two assets, A and B, with weights of 0.6 and 0.4 respectively, and expected returns of 10% and 8% respectively, the portfolio expected return would be:
Portfolio Expected Return = (0.6 x 10%) + (0.4 x 8%) = 9.2%
The variance of return of a portfolio is a measure of the degree of variability of the returns of the portfolio. It takes into account the weights and the covariance between the returns of the individual assets in the portfolio. It is calculated as follows:
Portfolio Variance of Return = ∑∑(Weight of Asset i x Weight of Asset j x Covariance between Asset i and Asset j)
For example, if a portfolio consists of two assets, A and B, with weights of 0.6 and 0.4 respectively, and a covariance of 0.02, the portfolio variance of return would be:
Portfolio Variance of Return = (0.6 x 0.6 x Covariance between A and A) + (0.6 x 0.4 x Covariance between A and B) + (0.4 x 0.6 x Covariance between B and A) + (0.4 x 0.4 x Covariance between B and B)
Portfolio Variance of Return = (0.6 x 0.6 x 0.05) + (0.6 x 0.4 x 0.02) + (0.4 x 0.6 x 0.02) + (0.4 x 0.4 x 0.03) = 0.032
The standard deviation of the portfolio return can be calculated by taking the square root of the portfolio variance of return.
Portfolio Expected Return = ∑(Weight of Asset i x Expected Return of Asset i)
For example, if a portfolio consists of two assets, A and B, with weights of 0.6 and 0.4 respectively, and expected returns of 10% and 8% respectively, the portfolio expected return would be:
Portfolio Expected Return = (0.6 x 10%) + (0.4 x 8%) = 9.2%
The variance of return of a portfolio is a measure of the degree of variability of the returns of the portfolio. It takes into account the weights and the covariance between the returns of the individual assets in the portfolio. It is calculated as follows:
Portfolio Variance of Return = ∑∑(Weight of Asset i x Weight of Asset j x Covariance between Asset i and Asset j)
For example, if a portfolio consists of two assets, A and B, with weights of 0.6 and 0.4 respectively, and a covariance of 0.02, the portfolio variance of return would be:
Portfolio Variance of Return = (0.6 x 0.6 x Covariance between A and A) + (0.6 x 0.4 x Covariance between A and B) + (0.4 x 0.6 x Covariance between B and A) + (0.4 x 0.4 x Covariance between B and B)
Portfolio Variance of Return = (0.6 x 0.6 x 0.05) + (0.6 x 0.4 x 0.02) + (0.4 x 0.6 x 0.02) + (0.4 x 0.4 x 0.03) = 0.032
The standard deviation of the portfolio return can be calculated by taking the square root of the portfolio variance of return.
CFA考试视频Portfolio Expected Return and Variance of ReturnCFA一级视频