Portfolio Expected Return and Variance of Return
479 播放时长:900
加载播放器...
Return,RjFirst= 7.50 + 12.50 + 3.75 = 23.75.
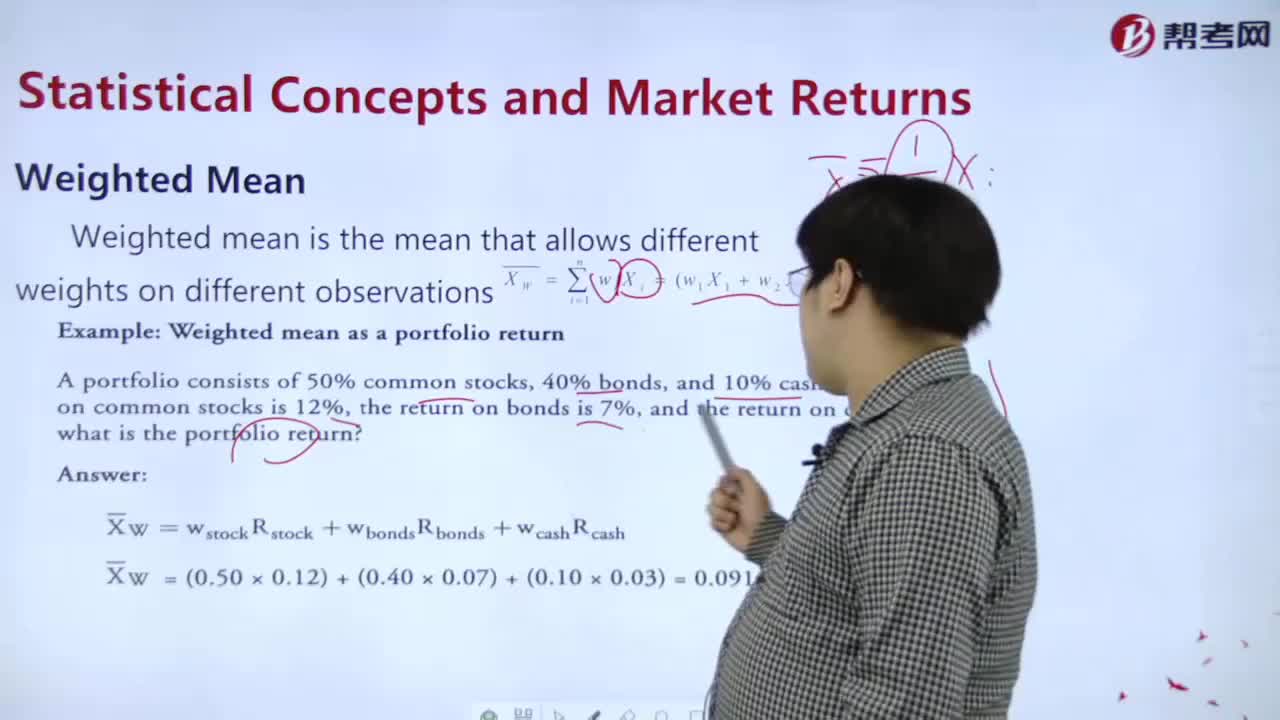
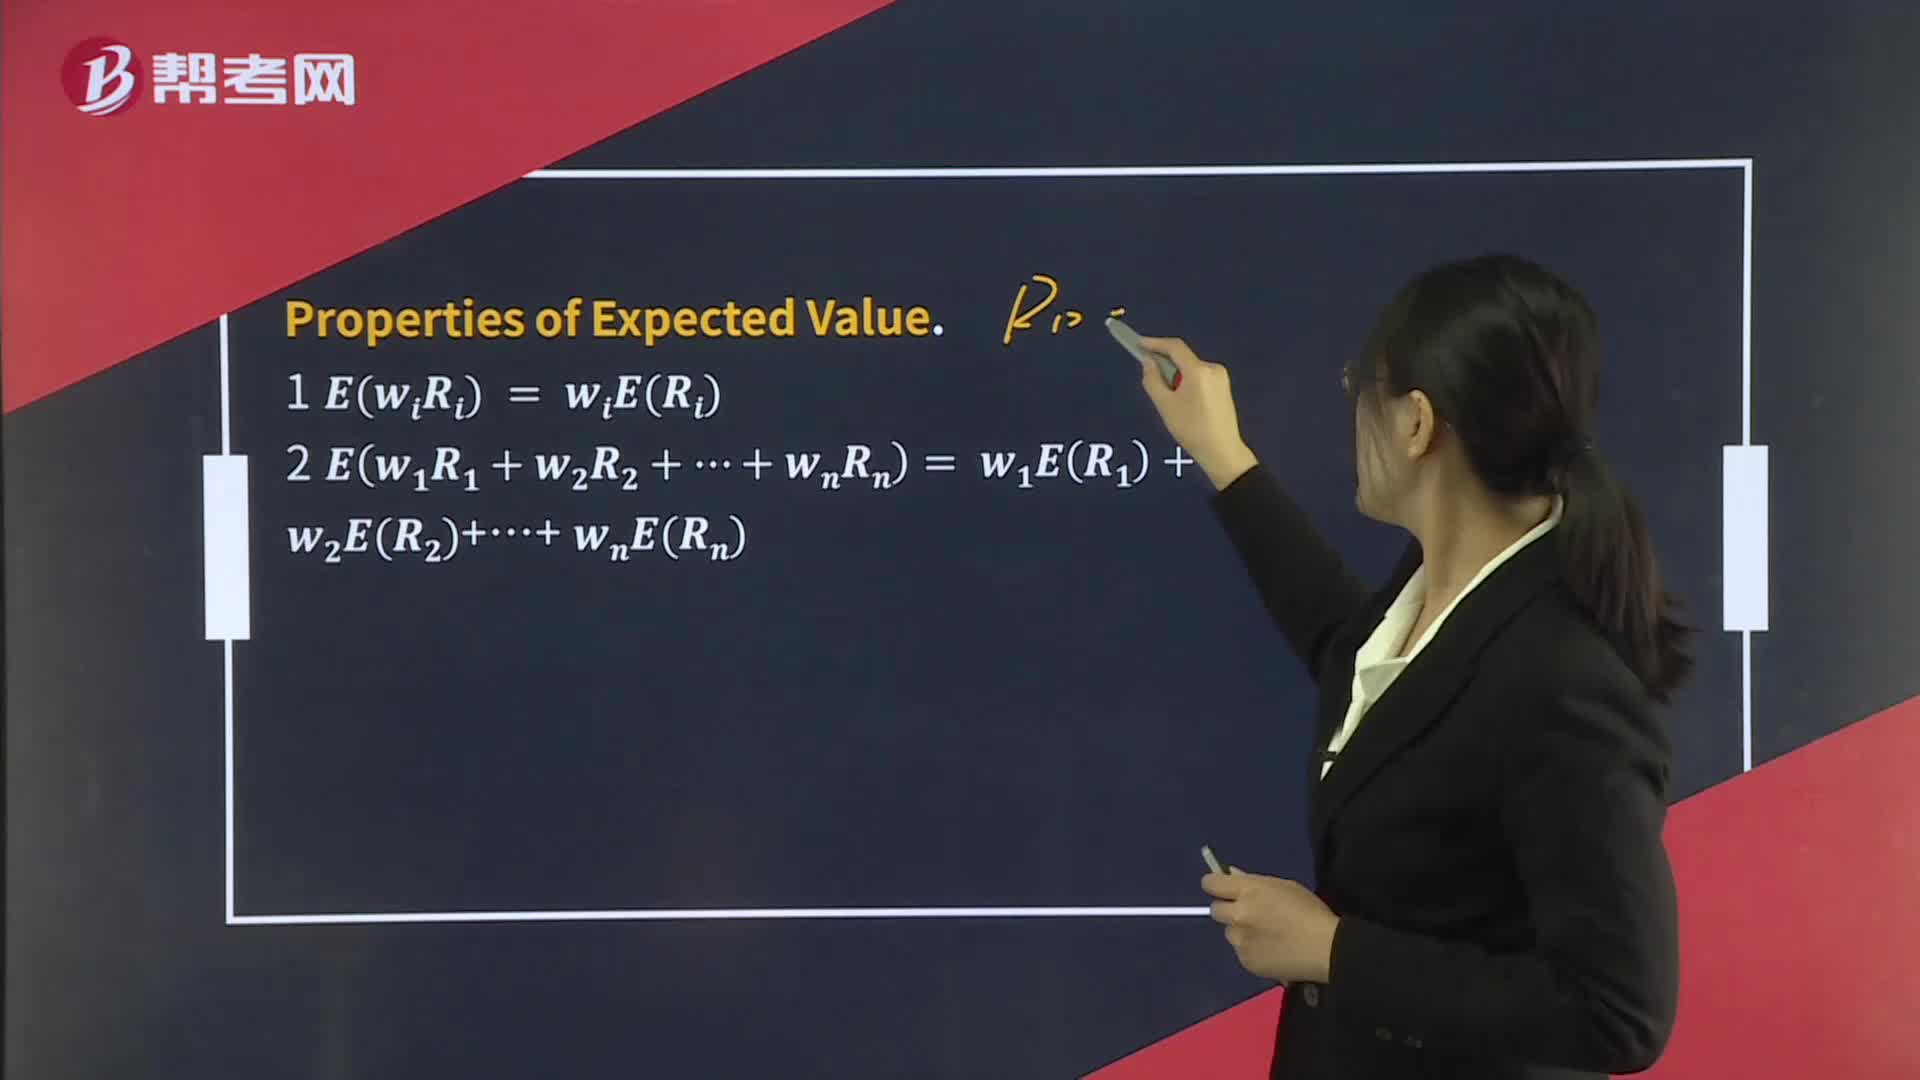
The expected return of a portfolio is the weighted average of the expected returns of its individual assets. It is calculated by multiplying the expected return of each asset by its weight in the portfolio and summing the results. For example, if a portfolio consists of two assets with expected returns of 10% and 15% and weights of 40% and 60% respectively, the expected return of the portfolio would be:
Expected return = (10% x 0.4) + (15% x 0.6) = 13%
The variance of return of a portfolio is a measure of the variability of the returns of the portfolio. It is calculated by taking the weighted sum of the variances of the individual assets in the portfolio, plus the weighted sum of the covariances between each pair of assets in the portfolio. The formula for the variance of return of a portfolio is:
Variance of return = w1^2 x σ1^2 + w2^2 x σ2^2 + 2w1w2 x σ1σ2 x ρ12
Where w1 and w2 are the weights of the two assets, σ1^2 and σ2^2 are the variances of the returns of the two assets, σ1σ2 is the covariance between the returns of the two assets, and ρ12 is the correlation coefficient between the returns of the two assets.
The standard deviation of return of a portfolio is the square root of its variance of return. It is a measure of the risk of the portfolio.
CFA考试视频Portfolio Expected Return and Variance of ReturnCFA一级视频