How to apply MWRR and TWRR?
274 播放时长:138
加载播放器...
How to apply MWRR and TWRR?
MWRR (Money-Weighted Rate of Return) and TWRR (Time-Weighted Rate of Return) are two methods used to calculate investment returns. Here are the steps to apply them:
MWRR:
1. Determine the cash flows: Identify the amount and timing of all cash flows (investments and withdrawals) during the investment period.
2. Calculate the net present value: Using the cash flows, calculate the net present value (NPV) of the investment.
3. Solve for the rate of return: Solve for the rate of return that makes the NPV equal to zero using a financial calculator or Excel.
TWRR:
1. Calculate the period returns: Divide the investment period into sub-periods and calculate the return for each sub-period.
2. Calculate the geometric mean: Calculate the geometric mean of the sub-period returns.
3. Adjust for external cash flows: Adjust the geometric mean for external cash flows (investments and withdrawals) using the formula: [(1 + geometric mean) / (1 + weighted cash flow)] - 1.
4. Calculate the TWRR: Add 1 to the adjusted geometric mean and raise it to the power of the number of sub-periods, then subtract 1 from the result.
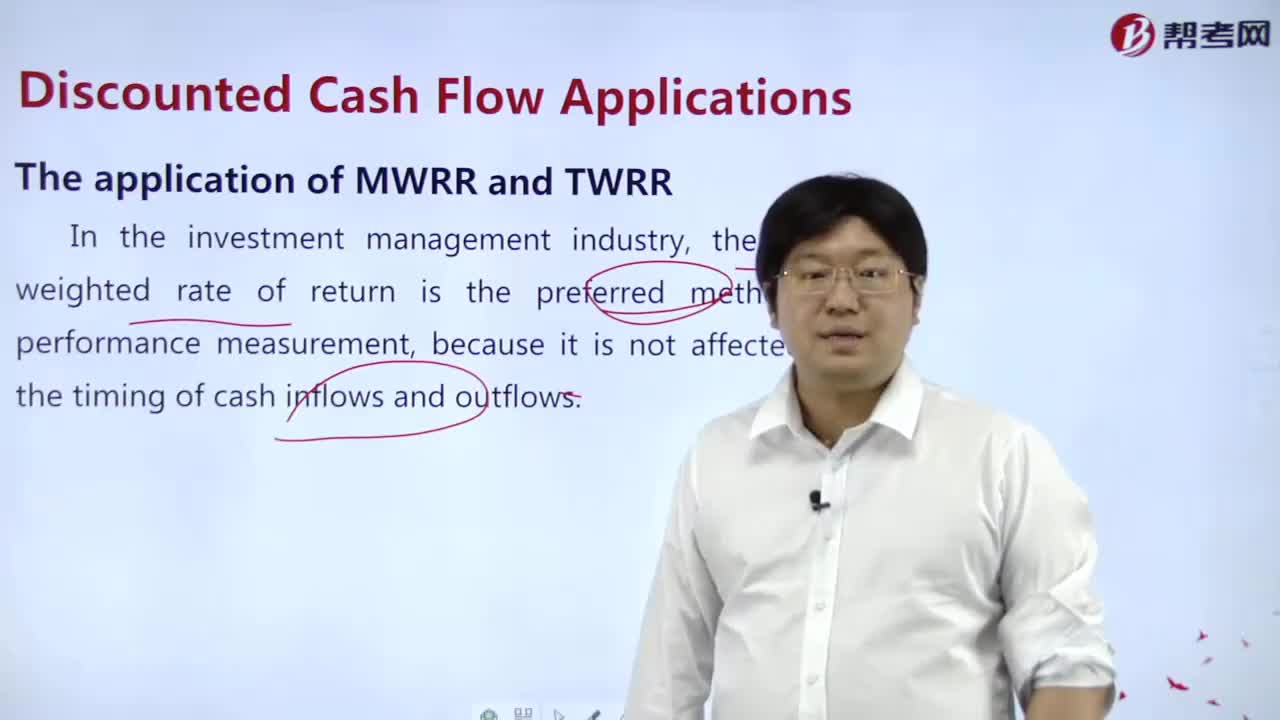
Note that MWRR is affected by the timing and size of cash flows, while TWRR is not. MWRR is more appropriate for evaluating the performance of individual portfolios, while TWRR is more appropriate for comparing the performance of different portfolios.
CFA考试视频CFA一级视频How to apply MWRR and TWRR?