Monte Carlo Simulation
324 播放时长:279
加载播放器...
Monte,planning:developing estimates of VaR:[Practiceanalysis.C.cause-and-effect relationships
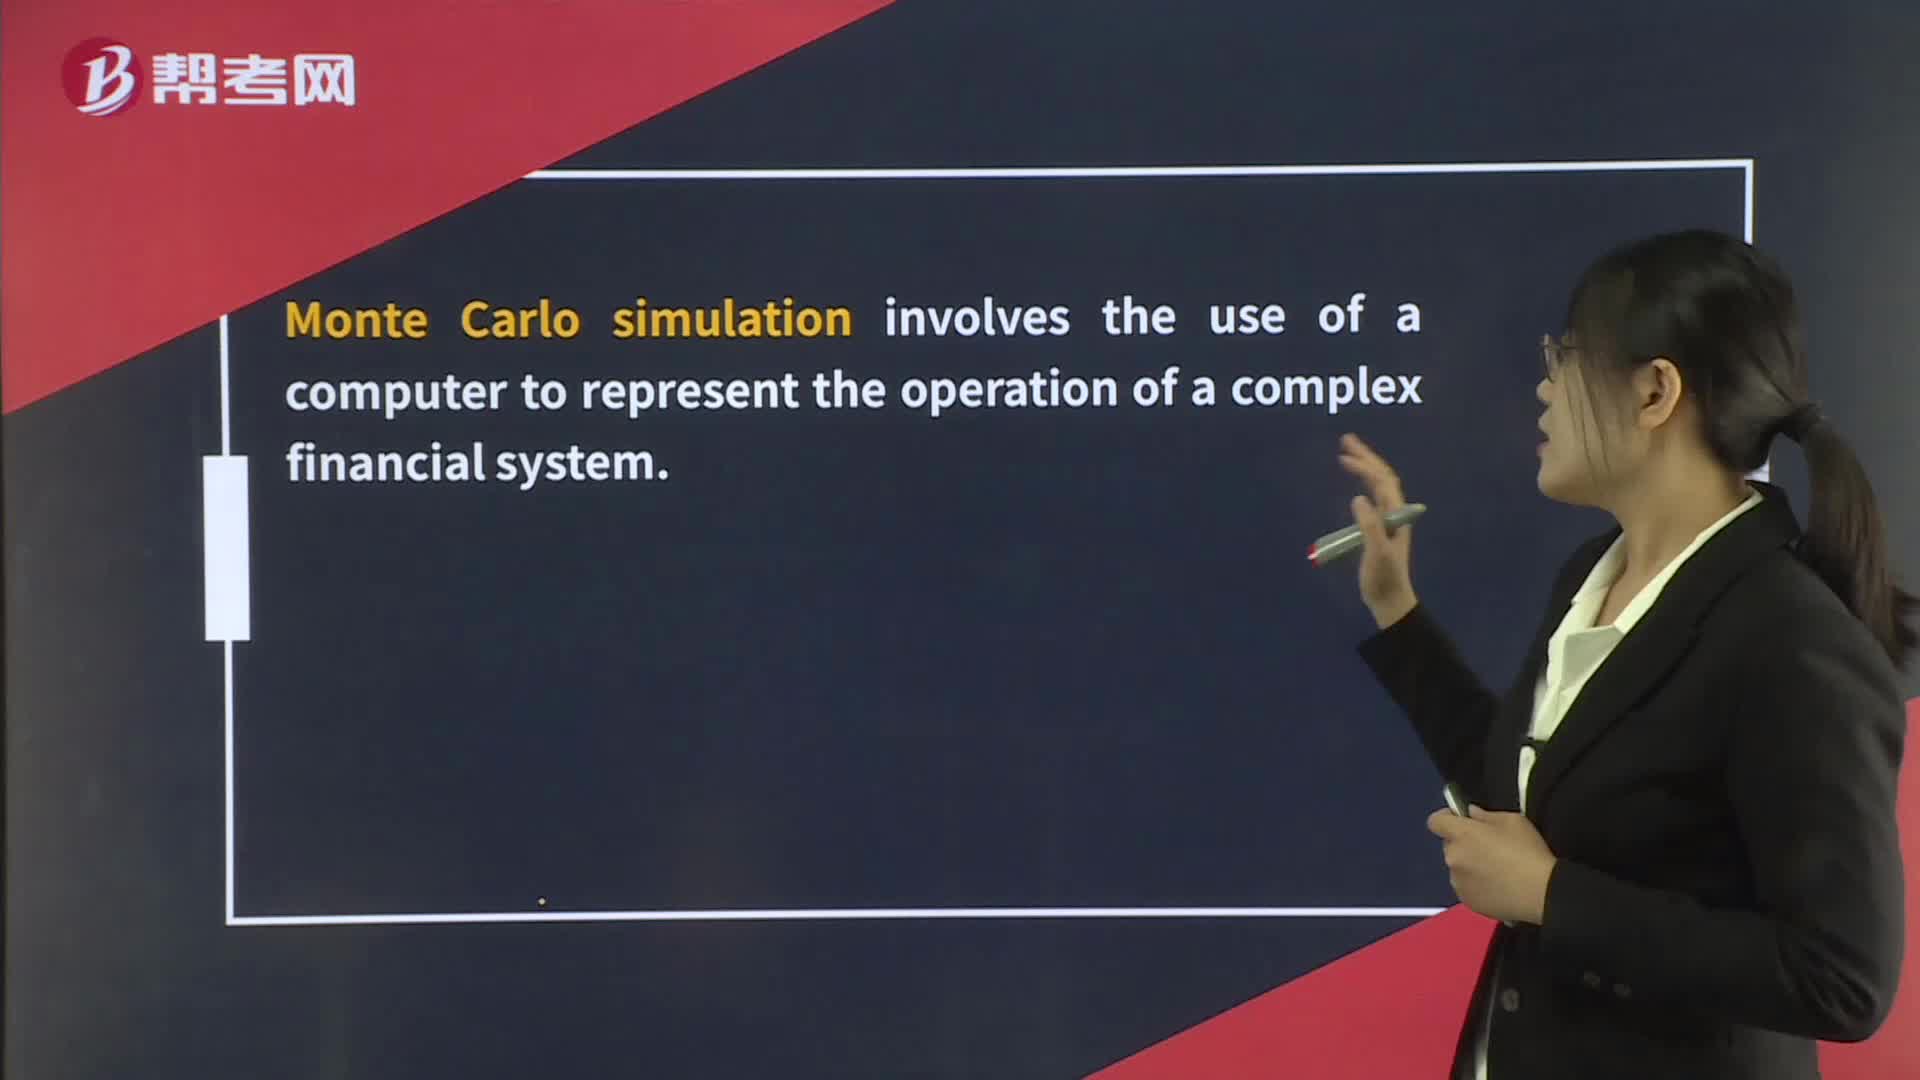
Monte Carlo simulation is a computational technique used to estimate the probability of different outcomes in a system that is subject to random variables. It involves running multiple simulations of the system, each with different randomly generated inputs, and then analyzing the results to determine the likelihood of different outcomes.
Monte Carlo simulation is commonly used in finance, engineering, and other fields where the behavior of a complex system is difficult to predict with certainty. For example, in finance, Monte Carlo simulation can be used to model the performance of an investment portfolio under different market conditions. In engineering, it can be used to model the behavior of a complex system, such as a bridge or a chemical plant, under different operating conditions.
The Monte Carlo simulation process typically involves the following steps:
1. Define the system to be modeled and the random variables that affect its behavior.
2. Generate a large number of random samples for each variable.
3. Run simulations of the system using the random samples as inputs.
4. Analyze the results of the simulations to estimate the probability of different outcomes.
Monte Carlo simulation can provide valuable insights into the behavior of complex systems and help decision-makers make more informed choices. However, it is important to note that the accuracy of the results depends on the accuracy of the inputs and assumptions used in the model.
Monte Carlo simulation is commonly used in finance, engineering, and other fields where the behavior of a complex system is difficult to predict with certainty. For example, in finance, Monte Carlo simulation can be used to model the performance of an investment portfolio under different market conditions. In engineering, it can be used to model the behavior of a complex system, such as a bridge or a chemical plant, under different operating conditions.
The Monte Carlo simulation process typically involves the following steps:
1. Define the system to be modeled and the random variables that affect its behavior.
2. Generate a large number of random samples for each variable.
3. Run simulations of the system using the random samples as inputs.
4. Analyze the results of the simulations to estimate the probability of different outcomes.
Monte Carlo simulation can provide valuable insights into the behavior of complex systems and help decision-makers make more informed choices. However, it is important to note that the accuracy of the results depends on the accuracy of the inputs and assumptions used in the model.
CFA考试视频Monte Carlo SimulationCFA一级视频