How to calculate MWRR and TWRR?
437 播放时长:109
加载播放器...
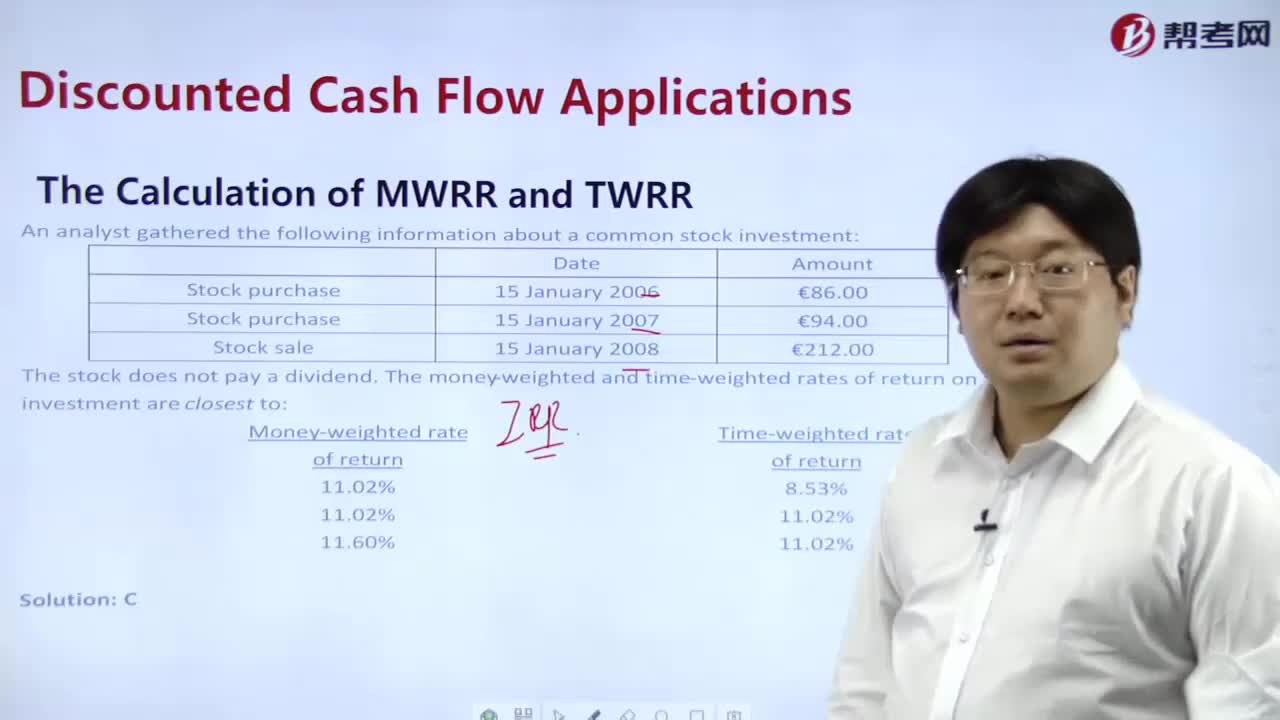
How to calculate MWRR and TWRR?
MWRR (Modified Dietz Method Weighted Rate of Return) and TWRR (Time-Weighted Rate of Return) are two methods used to calculate the rate of return on an investment portfolio. Here are the steps to calculate these two methods:
MWRR:
Step 1: Calculate the cash flows for the period. This includes all the cash inflows and outflows during the period.
Step 2: Calculate the weighted average time of the cash flows. This is the average time between the cash inflows and outflows.
Step 3: Calculate the change in the market value of the portfolio during the period.
Step 4: Calculate the MWRR using the following formula:
MWRR = (Ending Market Value - Beginning Market Value - Cash Flows) / (Beginning Market Value + (Weighted Average Cash Flows / 2))
TWRR:
Step 1: Calculate the market value of the portfolio at the beginning of the period.
Step 2: Calculate the market value of the portfolio at the end of the period.
Step 3: Calculate the time-weighted return for each sub-period by dividing the ending market value by the beginning market value and subtracting 1.
Step 4: Calculate the geometric average of the sub-period returns.
Step 5: Calculate the TWRR using the following formula:
TWRR = (1 + Geometric Average of Sub-Period Returns) ^ (365 / Number of Days) - 1
Note: The number of days can be adjusted depending on the time period being measured (e.g. 365 for a year, 90 for a quarter, etc.).
CFA考试视频CFA一级视频How to calculate MWRR and TWRR?